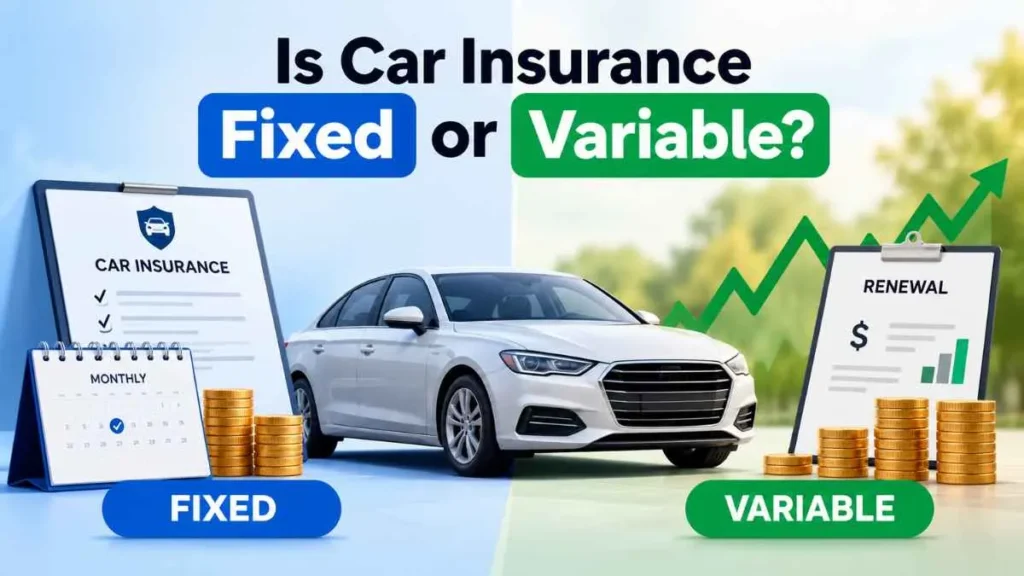
If you’re asking is car insurance fixed or variable, the best answer is: it is usually a fixed expense for budgeting during the current policy term, but the premium is not permanently fixed. Your insurer can change your rate at renewal based on factors such as your driving record, claims history, location, vehicle, mileage, coverage, and broader insurance costs.
Is Car Insurance a Fixed or Variable Expense?
For most drivers, car insurance is easier to treat as a fixed expense because the premium is generally predictable during the policy term. For example, if your six-month premium is $900, you can budget about $150 per month.
However, “fixed expense” does not mean “fixed price forever.” Your renewal premium can be higher or lower than the previous term.
Why Car Insurance Is Considered a Fixed Expense
A traditional auto insurance policy generally has a set premium for a specific coverage period. You may pay monthly, every six months, or annually, depending on your insurer and payment plan.
Your bill also does not normally change every time you drive. Driving an extra 100 miles in one month does not usually create a separate per-mile charge on a traditional policy.
Mileage can still be a rating factor when insurers determine your premium, however.
Why It Isn’t Permanently Fixed
Your premium can change when the policy renews. Insurers may reconsider your rate based on changes in your risk profile, claims costs, vehicle, location, mileage, coverage, or other rating factors.
Broader increases in repair, replacement, medical, theft, or weather-related claim costs can also affect insurance rates.
Key takeaway: Fixed for budgeting ≠ fixed forever.
Fixed Expense vs. Fixed Price
These terms are easy to confuse:
| Term | Meaning |
|---|---|
| Fixed expense | A predictable cost you can include in your budget. |
| Fixed price | An amount that remains unchanged for the specified period. |
| Variable expense | A cost that changes based on usage or circumstances. |
| Insurance premium | Generally predictable during a policy term but subject to change later. |
For example, a $900 six-month premium can be budgeted as $150 per month. If renewal increases it to $1,020, your new monthly budget equivalent becomes $170.
So, the expense is predictable for budgeting, while the price can change over time.
How Car Insurance Premiums Work
A car insurance premium is what you pay for insurance coverage. It is different from your deductible, which is the amount you generally pay toward a covered claim before the insurer pays its share, when a deductible applies.
Insurance companies do not simply calculate:
Car value = insurance price
Instead, insurers evaluate risk and expected claim costs. Common rating factors can include driving record, claims history, location, vehicle type, annual mileage, vehicle use, coverage, and deductibles. The factors insurers can use vary by state.
Your premium is also not a payment plan for future claims. If an insurer pays a covered $5,000 claim, you do not simply repay that $5,000 through future premiums. Your deductible, coverage, exclusions, and policy limits still apply. A claim may affect future rates, but that is a risk-rating issue rather than repayment of the claim.
What Can Make Your Car Insurance Premium Change?
Several factors can affect your premium:
- Driving record: Accidents, speeding tickets, and other violations can affect rates.
- Claims history: The frequency and severity of previous claims may influence pricing.
- Location: Accident rates, theft, weather, traffic, and local claim costs can vary by ZIP code.
- Vehicle: Repair costs, replacement costs, theft rates, and claim frequency can affect premiums.
- Mileage: Annual mileage and vehicle use can influence risk assessment.
- Coverage: Higher liability limits or additional coverage can increase costs.
- Deductible: A higher deductible can sometimes reduce the premium.
- Household changes: Adding a driver, teenage driver, or vehicle can change your rate.
- Insurer rate changes: Your premium can increase even when your own driving record has not changed.
Why Did My Car Insurance Go Up Without an Accident?
A clean driving record does not guarantee that your renewal price will stay the same.
Your insurer may face higher costs for vehicle repairs, replacement parts, medical claims, theft, weather losses, or other claims. Changes in the insurer’s approved rating plan can also affect renewal premiums.
That is why you can have the same car, no accident, and no ticket yet still receive a higher renewal quote.
Why Can Insurance Rise While Your Car Loses Value?
Your car’s depreciation does not automatically make insurance cheaper.
Liability coverage is concerned with the damage or injuries you may cause to others, not simply your vehicle’s resale value. For collision and comprehensive coverage, vehicle value matters, but insurers also consider expected claim costs.
An older vehicle can still have expensive parts, labor, technology, theft risk, or repair requirements. Therefore, an older car is not automatically cheaper to insure.
Does Driving More Make Car Insurance More Expensive?
Not usually like a fuel bill.
Traditional insurance generally does not charge you a separate amount for every mile driven each month. However, annual mileage can be used as a rating factor, and more driving can mean greater exposure to accidents. Business use may also be rated differently from personal use.
Is Pay-Per-Mile Insurance a Variable Expense?
Pay-per-mile insurance is an important exception.
Traditional insurance is generally more predictable during the policy term. Pay-per-mile insurance can combine a base charge with a mileage-based charge, making the cost more directly connected to how much you drive.
Usage-based insurance (UBI) can also use telematics to evaluate mileage and driving behavior such as braking, acceleration, time of day, or other data. Programs differ by insurer and state.
| Feature | Traditional Auto Insurance | Pay-Per-Mile / UBI |
|---|---|---|
| Policy-term cost | Generally predictable | May vary more |
| Mileage impact | Usually indirect | More direct in some programs |
| Renewal | Can change | Can change |
| Driving behavior | May be considered | Can be more directly measured |
How to Budget for Car Insurance
If your six-month premium is $900:
$900 ÷ 6 = $150 per month
If your annual premium is $1,800:
$1,800 ÷ 12 = $150 per month
These calculations help you budget for a periodic expense. Just leave some room for possible renewal changes.
Before renewal, review your coverage, deductibles, drivers, mileage, discounts, and available quotes.
Frequently Asked Questions
Is car insurance a fixed or variable expense?
For most drivers, it is best treated as a fixed expense for budgeting during the current policy term, but the premium can change at renewal.
Is car insurance a fixed cost?
It can be considered a fixed or periodic expense for household budgeting, but the underlying premium is not permanently fixed.
Can car insurance increase at renewal?
Yes. Your renewal premium can change because of personal rating factors, coverage, claims costs, location, vehicle factors, or broader insurance rate changes.
Does car insurance get cheaper as a car gets older?
Not necessarily. Depreciation can reduce some physical-damage exposure, but repair costs, theft risk, liability, and other rating factors still matter.
Does driving more increase car insurance?
Annual mileage can influence your premium, but traditional insurance usually does not work as a monthly per-mile bill.
Bottom Line: Is Car Insurance Fixed or Variable?
For most U.S. drivers, car insurance is a fixed expense for budgeting during the current policy term, but the premium is not permanently fixed.
Current policy → generally predictable
Renewal → can change
Pay-per-mile/UBI → potentially more variable
That distinction is the simplest way to understand whether car insurance is fixed or variable.
Read Also:-Why Is Car Insurance So Expensive in Massachusetts